How to Improve Your CIBIL Score in Bangalore Before Applying for a Home Loan
Table of content
- Introduction
- Why Is Your CIBIL Score Important for a Home Loan?
- What Is the Minimum CIBIL Score for a Home Loan in Bangalore?
- CIBIL Score Improvement in Bangalore: Start by Checking Your Credit Report
- How to Improve CIBIL Score in Bangalore Before Applying for a Loan
- Home Loan CIBIL Score Improvement: Reduce Credit Card Usage and Existing Debt
- Correct Credit Report Errors Before Applying for a Home Loan
- When Should You Contact a CIBIL Score Improvement Agency in Bangalore?
- Prepare Your Finances Before Applying for a Home Loan
- How Long Does It Take to Improve Your CIBIL Score?
- Conclusion
- Frequently Asked Questions
Introduction
Buying a home is a big dream for many families in Bangalore. Whether you are planning to buy an apartment in Whitefield or a house in Yelahanka, getting a home loan is often an important part of the journey. But before approving your application, banks look at your credit history and CIBIL score to understand how you manage borrowed money. If your score is low, you may face difficulties getting a loan or receiving favourable terms. The good news is that you can take practical steps to improve your credit score before a home loan and prepare yourself financially.
Why Is Your CIBIL Score Important for a Home Loan?
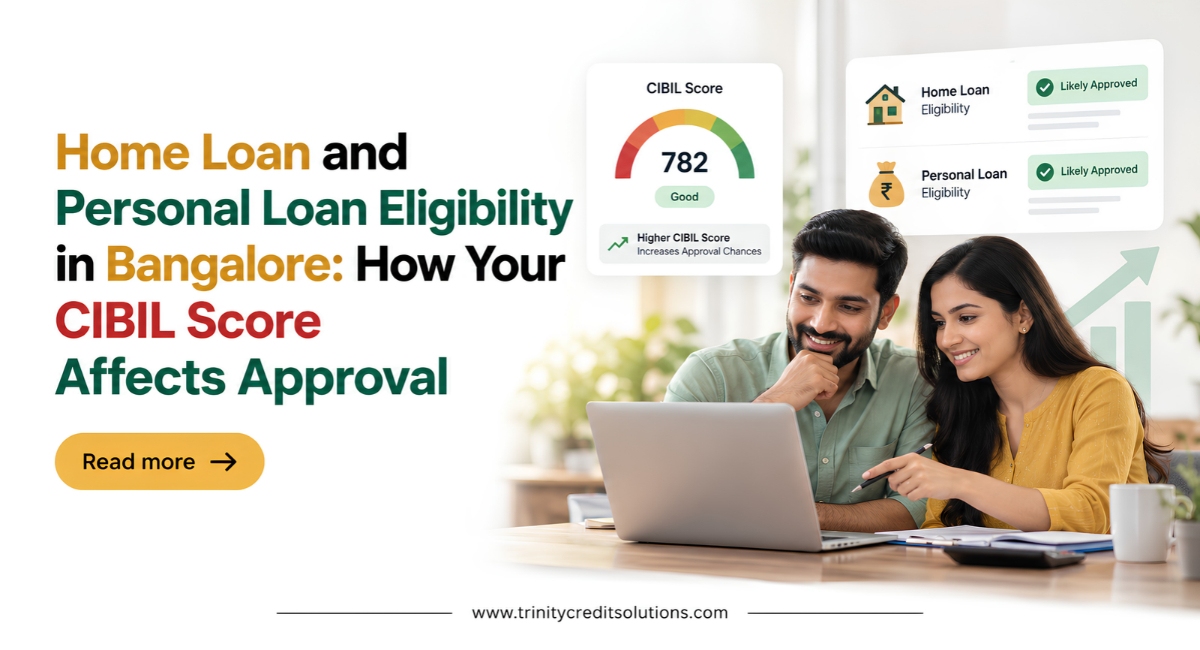
Your CIBIL score is a three-digit number ranging from 300 to 900 that reflects your credit history. Banks use this score to understand how regularly you repay loans and credit card bills. A higher score generally indicates responsible credit behaviour and can improve your chances of getting favourable home loan terms.
Your credit score can also influence the interest rate offered by a lender. Even a small difference in interest rates can affect the total amount you repay over a long home loan tenure. This is why checking your credit health before approaching a bank is important, especially when you are planning a major purchase.
What Is the Minimum CIBIL Score for a Home Loan in Bangalore?
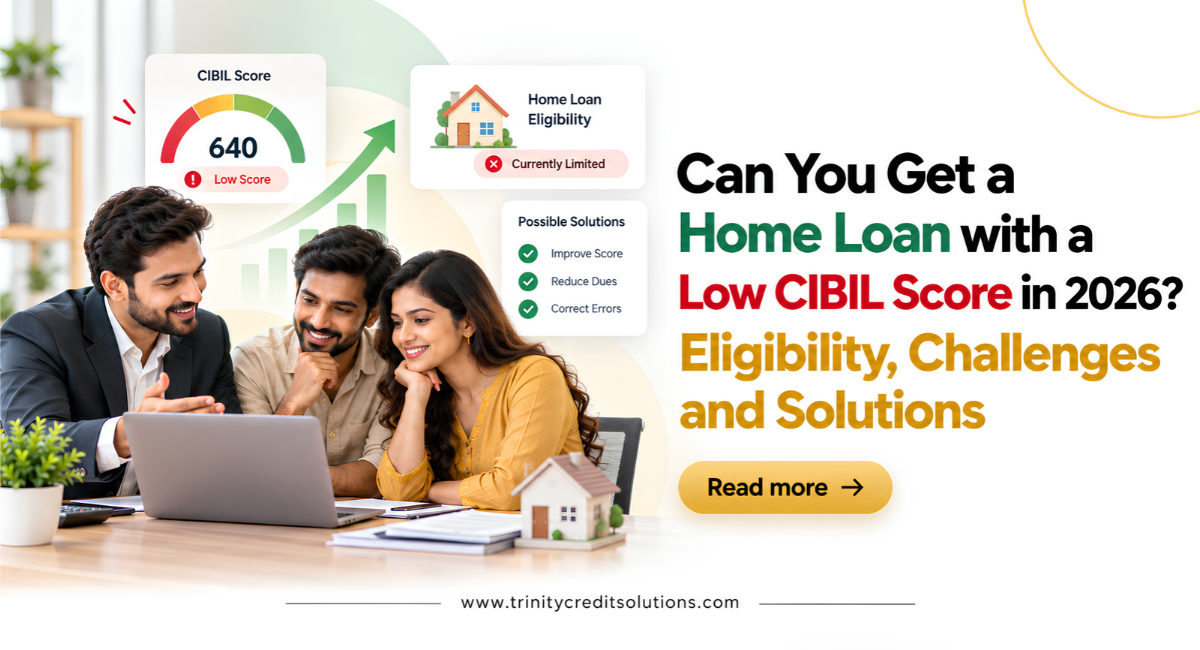
There is no single minimum CIBIL score for home loan approval that applies to every bank in India. However, a score of 750 or above is generally considered a strong position for many home loan applicants. Some lenders may consider applications with lower scores, depending on the applicant's income, repayment capacity and credit history.
If your score is below 700, it is worth reviewing your financial situation before applying. A lower score does not automatically mean rejection, but it may lead to stricter eligibility checks or less favourable loan terms. Your employment stability, existing EMIs, down payment and property details also influence the bank's final decision.
CIBIL Score Improvement in Bangalore: Start by Checking Your Credit Report
The first step towards CIBIL Score Improvement in Bangalore is understanding your current credit position. Your CIBIL report contains information about existing loans, credit cards, repayment history and enquiries made by lenders. Checking this report helps you identify overdue payments, high outstanding balances and possible reporting errors.
Under RBI guidelines, eligible individuals can receive one free full credit report, including their score, every calendar year from each credit information company holding their data. Review your report carefully before applying for a home loan so that you have time to address any concerns.
How to Improve CIBIL Score in Bangalore Before Applying for a Loan
Improving your credit score starts with consistent financial habits. If you want to understand how to increase CIBIL score for home loan applications, focus on paying your dues on time and managing existing credit responsibly. These habits help lenders see that you can handle monthly repayment commitments.
Pay Every EMI and Credit Card Bill on Time
Missing an EMI or credit card payment can negatively affect your credit history. Set reminders or activate automatic payments to avoid missing due dates. If you already have overdue amounts, contact the lender and arrange to clear them as soon as possible. Regular payments over time can help strengthen your repayment record.
Avoid Applying for Multiple Loans at Once
Every time you formally apply for credit, the lender may check your credit report. Several applications within a short period can affect your score and make lenders cautious. Before applying for a home loan, avoid unnecessary personal loans or new credit cards and focus on maintaining your existing accounts.
Home Loan CIBIL Score Improvement: Reduce Credit Card Usage and Existing Debt
One important part of Home Loan CIBIL Score Improvement is managing your outstanding debt. Using a large portion of your available credit card limit can affect your credit score, even when you are making payments regularly. Keeping balances low shows lenders that you are not heavily dependent on borrowed money.
Keep Your Credit Card Balances Low
Try to keep your credit card usage comfortably below your available limit. For example, if your card limit is ₹1,00,000, keeping the balance below ₹30,000 can be a useful planning target, although it does not guarantee a particular score. Paying the full statement amount by the due date also helps you avoid interest charges.
Reduce Existing Loan Burdens Where Possible
Before applying for a home loan, review your personal loans, vehicle loans and other monthly commitments. If you have enough savings, reducing outstanding debt may improve your repayment capacity. However, avoid using your entire emergency fund to close loans, as you will also need money for your down payment and home-related expenses.
Correct Credit Report Errors Before Applying for a Home Loan
Sometimes, a low score may be partly linked to incorrect information in your credit report. You might find a closed loan showing as active, a payment incorrectly marked as overdue or an unfamiliar account. Such errors can affect how lenders assess your application, making it important to review your report carefully.
If you notice inaccurate information, contact the concerned lender and raise a dispute. The lender must verify the information before it can be corrected. Credit report disputes generally have a 30-day resolution framework, but genuine late payments or defaults cannot simply be deleted because they affect your score.
When Should You Contact a CIBIL Score Improvement Agency in Bangalore?
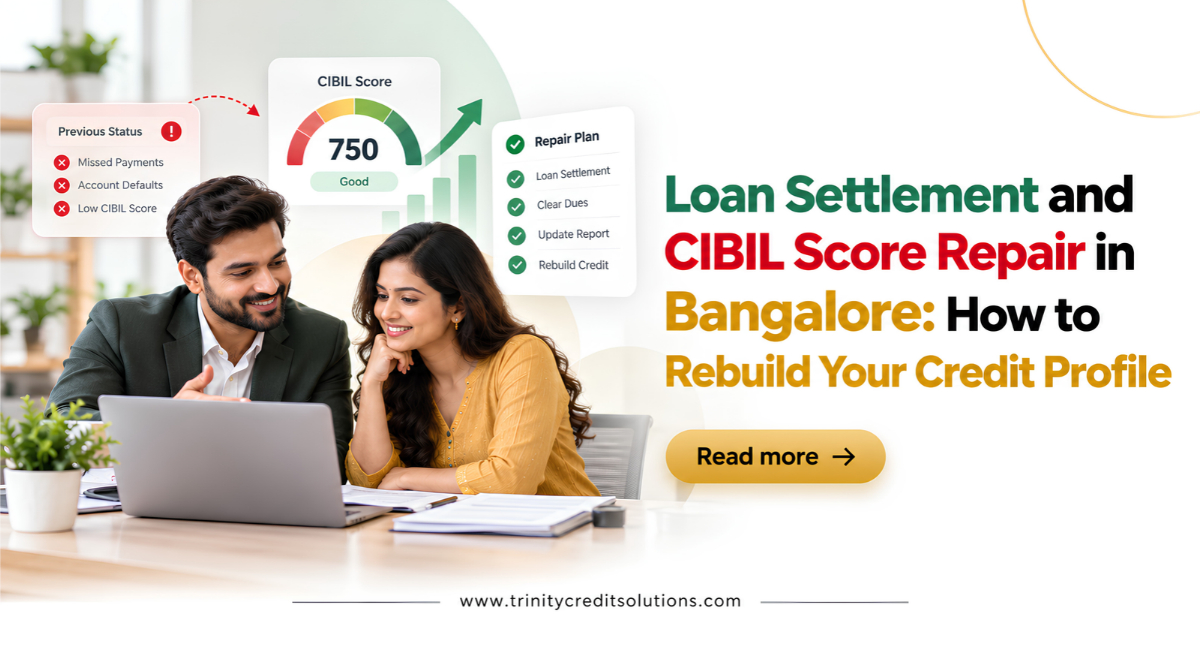
Managing multiple loans, understanding credit report details and resolving reporting errors can sometimes become confusing. A professional CIBIL Score Improvement Agency in Bangalore can help you review your credit profile, identify possible issues and understand the steps needed to improve your financial position before a home loan application.
Reliable credit score improvement services in Bangalore should focus on proper report analysis, dispute assistance and realistic financial guidance. At Trinity Credit Solutions, the team provides credit report analysis, personalised improvement guidance and assistance with credit-related concerns. While professional support can simplify the process, no agency can guarantee a particular score increase or home loan approval.
Prepare Your Finances Before Applying for a Home Loan
A healthy credit score is important, but banks also look at whether you can comfortably repay the loan. Before submitting your application, calculate your monthly income, household expenses and existing EMIs. This will help you understand how much you can realistically afford to borrow without placing too much pressure on your finances.
It is also useful to save for a sufficient down payment and keep important documents ready, including income proof, bank statements and existing loan details. If you have a low CIBIL score, home loan eligibility will depend on several factors beyond the score itself. Preparing your finances properly can make discussions with lenders easier and more productive.
How Long Does It Take to Improve Your CIBIL Score?
Credit score improvement is not instant. If your report contains an incorrect entry, the score may change after the lender verifies and corrects the information. However, improving a score affected by missed payments, high balances or previous defaults usually requires consistent financial behaviour over time.
Ideally, start reviewing your credit health at least three to six months before you plan to apply for a home loan. This gives you time to reduce outstanding balances, address disputes and build a more consistent repayment record. Some improvements may appear sooner, while serious credit issues can take much longer. There is no fixed timeline or guaranteed number of points you can gain.
Conclusion
A better CIBIL score can make your home loan journey smoother by helping lenders understand your repayment history and financial discipline. Paying bills on time, reducing debt, correcting reporting errors and planning your finances early can put you in a stronger position before applying for a loan.
If you are unsure where to begin, Trinity Credit Solutions can help you understand your credit report and identify suitable improvement steps. Get a free credit review and take a more informed step towards your home ownership goals.
Check Your Credit Health with Trinity Credit Solutions
Call Our Credit Experts: +91 70228 24546
Get a Free Credit Review Today!
Frequently Asked Questions
When should I start improving my credit score before buying a house?
Starting three to six months before applying is a sensible approach for many borrowers. If you have serious overdue payments, defaults or complicated credit report errors, you may need more time to strengthen your financial profile.
Should I close all my credit cards before applying for a home loan?
Not necessarily. Closing a long-standing credit card may affect your available credit limit and credit history. It is often better to maintain manageable balances and make payments regularly. Review your individual circumstances before closing an account.
Can a CIBIL consultant help improve my home loan eligibility?
A credit consultant can help you understand your report, identify inaccuracies and plan practical steps to improve your credit profile. Consultants cannot change accurate repayment records or guarantee loan approval. The final lending decision always rests with the bank or financial institution.
Does checking my CIBIL score frequently reduce it?
No. Checking your own CIBIL score is considered a soft enquiry and does not lower your score. However, formal credit applications can result in lender enquiries that may affect your credit profile.
How can I improve my CIBIL score quickly before a home loan?
Start by clearing overdue payments, reducing credit card balances and checking your credit report for mistakes. Avoid unnecessary credit applications during this period. These steps may help, but the amount and speed of improvement depend on your individual credit history.
Can I get a home loan with a CIBIL score of 650?
Some lenders may consider applicants with a score of 650, but approval is not guaranteed. They may examine your income, employment stability, down payment and existing liabilities more carefully. Improving your score before applying can help strengthen your application.
What is a good CIBIL score for a home loan in Bangalore?
A CIBIL score of 750 or above is generally considered favourable for home loan applications. However, each lender has its own eligibility requirements, and approval also depends on income, existing debt and repayment capacity.
Trinity