Home Loan Balance Transfer in 2026: Can a Better CIBIL Score Help You Get a Lower Interest Rate?
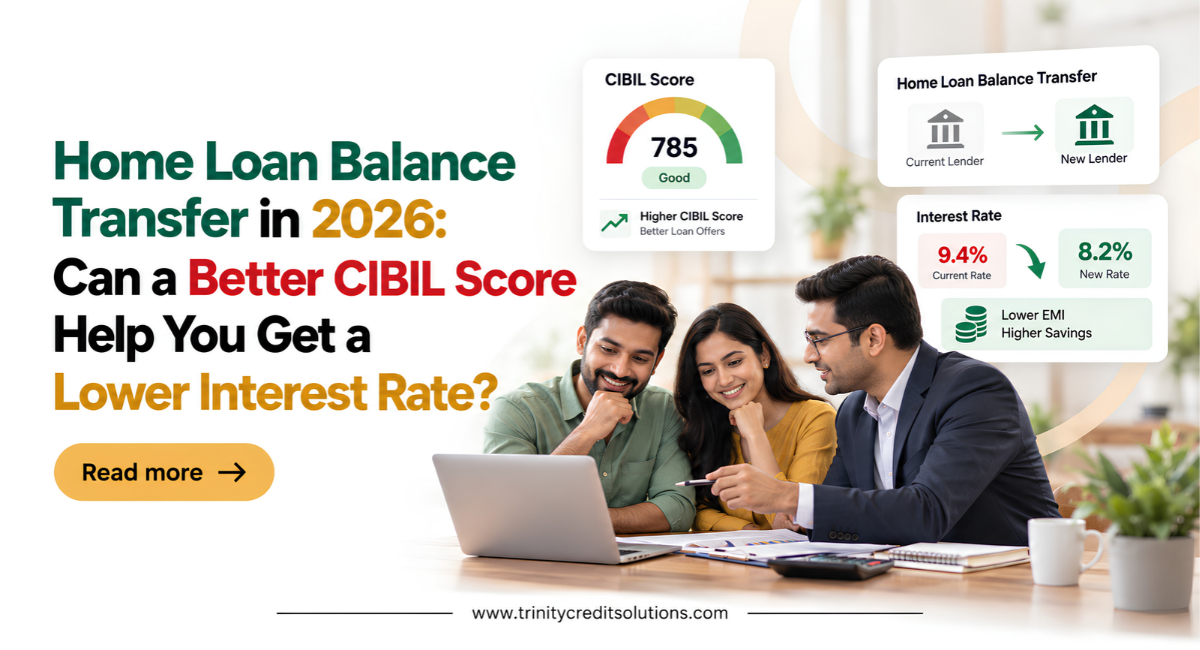
Table of content
1. Introduction
2. What Is a Home Loan Balance Transfer?
3. How Does Your CIBIL Score Affect Home Loan Interest Rates?
4. What CIBIL Score Is Needed for a Home Loan Balance Transfer?
5. Home Loan Balance Transfer Eligibility in 2026
6. How to Reduce Your Home Loan Interest Rate
7. When Should You Consider a Home Loan Balance Transfer?
8. Mistakes to Avoid Before Transferring Your Home Loan
9. Frequently Asked Questions
10.Conclusion
Introduction
Buying a home is a big achievement, but paying the home loan EMI every month can be a long financial responsibility. When interest rates are high, even a small difference in the rate can increase the total amount you pay over the years. Many homeowners wonder whether they can move their existing loan to another bank offering a lower interest rate. They also want to know whether improving their CIBIL score can help them get a better offer.
A Home Loan Balance Transfer 2026 may be a useful option for eligible borrowers who want to reduce their interest costs. However, a balance transfer is not suitable for everyone. Your credit score, repayment history, outstanding loan amount and transfer charges all matter.This guide explains how balance transfers work and what you should check before making a decision.
What Is a Home Loan Balance Transfer?
A home loan balance transfer means moving your existing home loan from one bank or financial institution to another. People usually consider this option when another lender offers a lower interest rate or more suitable repayment terms. For example, suppose you have a home loan with an annual interest rate of 9.5%. Another bank may offer you an interest rate of 8.5%, depending on your eligibility.
You can apply to transfer your remaining loan amount to the new bank. If your application is approved, the new lender generally pays the outstanding amount to your existing lender. You then start paying your EMIs to the new lender. The main purpose is to reduce borrowing costs or make repayments more manageable. However, transferring a home loan may involve processing fees, property verification charges and other expenses. Before applying, understand your financial position and review your credit history. You can explore the Credit Health Checkup service from Trinity Credit Solutions to understand your credit profile.
How Does Your CIBIL Score Affect Home Loan Interest Rates?
Your CIBIL score helps banks understand how you have managed loans and credit cards in the past. A higher score generally indicates that you have maintained a good repayment history. For example, a borrower with a score of 780 and regular EMI payments may appear less risky to a lender than someone with a score of 620 and several missed payments.
The Credit score impact on home loan interest depends on the lender's policies and how it evaluates your financial situation. Some banks offer different interest rates based on a borrower's credit profile. A better score may help you qualify for a more competitive offer, but it does not guarantee the lowest rate. Banks also review your income, employment, existing EMIs and property details. According to TransUnion CIBIL, your credit score is an important factor lenders consider when evaluating loan applications. Maintaining timely repayments and avoiding unnecessary borrowing can help you build a healthier credit profile.
What CIBIL Score Is Needed for a Home Loan Balance Transfer?
The CIBIL Score for Home Loan Balance Transfer is an important part of the application process. However, there is no single minimum CIBIL score that every bank follows. Many lenders consider a score of 750 or above favourable. Borrowers with lower scores may still qualify, depending on their overall financial situation.
Here is a general guide:
CIBIL Score General Credit Profile
750–900 Stronger chances of competitive offers
700–749 May qualify based on other conditions
650–699 Lenders may conduct additional checks
600–649 Approval may be more difficult
Below 600 Higher chances of rejection
These ranges are only general guidance, not official balance transfer eligibility rules. If your score is lower than expected, check your credit report before applying. Look for missed payments, high credit card balances or incorrect loan information. Correcting genuine reporting errors and maintaining regular repayments may help improve your credit profile over time. You can also review your credit history through the Individual Credit Report service.
Home Loan Balance Transfer Eligibility in 2026
Home loan balance transfer eligibility depends on more than your CIBIL score. Banks need to know whether you can comfortably repay the transferred loan.
Income and Employment: Lenders generally review your monthly income and employment stability. Salaried borrowers may need salary slips, bank statements and employment details. Self-employed borrowers may need income tax returns and business-related documents.
Existing Loan Repayment History: Regular EMI payments can support your application. If you have missed several payments or have overdue amounts, the new lender may consider your application risky.
Outstanding Loan Amount and Tenure: Banks also check how much you still owe and how many years remain on your loan. A larger outstanding amount with a longer remaining tenure may offer greater potential interest savings.
Property Documents: The new lender may verify property ownership, legal documents and property valuation. Make sure your documents are complete and accurate before applying. Meeting these conditions does not guarantee approval, but it can help you prepare a stronger application.
How to Reduce Your Home Loan Interest Rate
Many borrowers search for how to reduce their home loan interest rate when their existing EMI becomes difficult to manage.A balance transfer is one option, but it is important to compare the actual savings. Suppose you have an outstanding home loan of ₹30 lakh with 15 years remaining.
Loan Details Existing Loan New Loan
Outstanding amount ₹30,00,000 ₹30,00,000
Annual interest rate 9.5% 8.5%
Remaining tenure 15 years 15 years
Approximate monthly EMI ₹31,327 ₹29,542
In this example, the monthly saving is approximately ₹1,785. Over 15 years, this could mean around ₹3.21 lakh in lower repayments before transfer costs, assuming the rates remain unchanged. These figures are illustrative. Actual savings depend on your lender's terms, interest rate changes and applicable charges. Before transferring, ask your existing lender whether it can offer a lower rate. Sometimes, your current bank may agree to revise the rate without requiring a full loan transfer. If you decide to compare lenders, request a complete breakdown of the new loan's charges and repayment terms.
When Should You Consider a Home Loan Balance Transfer?
A balance transfer may be worth considering when you have a large outstanding loan amount and several years of repayments remaining. In such situations, even a small reduction in the interest rate can create meaningful savings. However, if your home loan is almost fully repaid, transferring it may not provide enough benefit to cover the costs.
For borrowers considering a Home Loan Balance Transfer 2026, the decision should depend on the total financial benefit. Think about your monthly EMI, remaining tenure, transfer charges and total interest payable. Also check whether the new lender offers suitable customer support and clear repayment terms. A longer tenure may reduce your monthly EMI, but it can increase the total interest you pay. If you are unsure about your credit position, the Credit Analyzer service can help you understand the information recorded in your credit report. Choose a transfer only when it supports your long-term financial plans.
Mistakes to Avoid Before Transferring Your Home Loan
One common mistake is selecting a lender only because it advertises a lower interest rate. The advertised rate may not be available to every borrower. Another mistake is ignoring processing fees, legal expenses and other transfer-related charges. These costs can reduce your actual savings. Some borrowers also extend their repayment tenure without calculating the additional interest they may pay.
Avoid applying to several lenders without checking their eligibility requirements. Multiple loan enquiries may affect your credit profile. It is also important to read your existing loan agreement before making a decision. Applicable RBI rules generally prohibit certain foreclosure or prepayment charges on floating-rate loans, but the exact protection depends on the loan and borrower category. You can refer to the Reserve Bank of India for official banking regulations and borrower guidance. Careful comparison can help you avoid unnecessary expenses.
Conclusion: Make the Right Choice for Your Home Loan
A home loan balance transfer can help you save on interest and reduce your monthly EMI. However, it is important to check your CIBIL score, remaining loan amount and transfer charges before making a decision. Compare different lenders and choose an option that suits your budget. A little planning today can help you manage your home loan more comfortably in the coming years.
Planning a Home Loan Balance Transfer 2026? Trinity Credit Solutions can help you understand your credit report and take steps to improve your credit health. Contact us to learn more and make informed decisions about your financial future.
Frequently Asked Questions
Does a home loan balance transfer affect my CIBIL score?
The new lender may make a hard credit enquiry. Your new loan account and future repayment history can also affect your credit profile.
Can I transfer my home loan after one year?
Some lenders may consider a balance transfer after one year of regular repayments. The actual requirements vary between lenders.
Is a home loan balance transfer free?
Not always. Processing fees, property valuation charges and other expenses may apply. Check the complete cost before transferring.
Will a higher CIBIL score help me get a lower interest rate?
A higher score may improve your chances of receiving a competitive interest rate. However, the final offer depends on the lender's policies and your overall financial profile.
Can I transfer my home loan with a 700 CIBIL score?
Yes, some lenders may consider borrowers with a score of 700. Approval depends on income, repayment history, outstanding debt and the lender's eligibility requirements.
Trinity